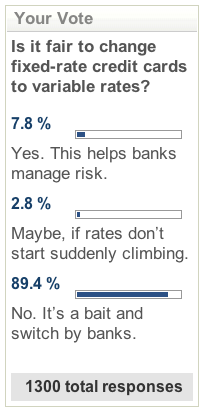









Video features Peter Meyer. No mention of the no opt out clause not being allowed, no mention of Chase Bank Pro-Active services, no mention of all the class action lawsuits that have been initiated.
Showing posts with label raise monthly minimum payment. Show all posts
Showing posts with label raise monthly minimum payment. Show all posts
Monday, August 3, 2009
Chase Bank YouTube Video about the 2% to 5% raise in the monthly minimum payment.


Friday, July 24, 2009
Chase Bank offers ProActive Solutions for Customers who Cannot Afford the 2% to 5% Monthly Minimum Payment.
(Update - Oct. 8, 2010 - Please go to this article as well to learn about the Chase Bank Balance Liquidation Program)
I just spoke with Chase Bank Credit Card Pro-Active Solutions Department. I did not go through the actual process of requesting a credit card "loan modification", but you can. The loan modification is for anyone who cannot afford the Chase Bank 2% to 5% raise in the monthly minimum payment on their low interest credit card loan.
Basically, you will be asked what your income is. Your deal will be based on your income and your ability to pay back the loan within a five year period. My opinion is that they are not verifying income. However, if you lie about your income and get a new deal, and then can't make the payments on the new deal, you won't be eligible for any additional modification for five years, and your account will probably go to default.
If you lie about your income, but can still make the payments on time every month until you pay off the loan, then, whatever, whatever. Ultimately, Chase Bank IS STEALING FROM YOU because they are forcing you to accept an accelerated paydown of your low interest rate credit card if it cause you to take longer to pay down other debt that is at a higher interest rate! However, a five year deal is better than either defaulting or accepting their 5% monthly minimum payment program if you cannot afford to pay down the debt that fast, or have to lower your payments on other debts that have a higher revolving interest rate charge.
I really don't like that everybody that is about to have their monthly minimum payment raised from 2% to 5% is NOT being notified about the five year plan. Only the bare minimum who check out a blog like this will discover this program. I think not notifying EACH AND EVERY CUSTOMER about the five year deal is deceptive. Everyone who was offered a similar type of low interest, life of the loan credit card offer (a life of the loan percentage rate of anywhere from 1.99 to 5.99 for the life of the loan) should be notified about the five year deal, so why doesn't Chase Bank just offer a one size fits all INCENTIVE BASED credit card debt paydown plan?
In the meantime, the best plan you can get from Chase Bank appears to be the five year deal. Please understand that you will be making that same size payment each month for the next five years AND your card will be CLOSED to new activity of any kind! You should however, retain the interest rate you are currently paying, and in some instances, apparently people are getting even lower interest rate offers.
You can pad down the payment on your five year deal by first making a bigger than normal payment to the account before asking for the five year deal.
I'm still going to ask for arbitration, but for most of you, Chase Bank ProActive Solutions may be the way to go. Allegedly, one can ask for ProActive Solutions at any time as long as their account REMAINS in good standing.
Chase Bank's Pro Active Solution phone number is... 866-351-0182, Pro Active hours of operation, Eastern Standard Time are, Mon-Thur 8AM to 10PM, Friday 8AM to 7PM, Saturday, 8AM to 5PM, Sunday 9AM-10PM
If you go through the process, please leave a comment here as to what your deal was, you can leave the comment anonymously if you wish.
(Edit update - I ended up going for the five year program. I made one payment at the 5% monthly minimum payment, and then I applied for the five year deal. That one 5% monthly minimum payment caused my five year plan to lower by I think it was 10 dollars a month over what it would have been had I not made that one bigger payment first.)
Wednesday, July 22, 2009
Is Chase Bank playing favorites, allowing some customers excellent solutions to their monthly minimum payment increase while others get nothing?
I have been informed there are two Chase Bank super special secret sauce solution phone numbers where one can call and get a favorable result to the catastrophic Chase Bank's raising of the monthly minimum payment from 2% to 5% on their most prudent, never late making a payment customers.
I just don't like the idea that Chase Bank is willing to secretly "fix" a very public wrong that they have already committed, and continue to commit, for only a select few.
Unless Jamie Dimon PERSONALLY APOLOGIZES to the 1 to 2 million salt of the earth Chase Bank customers that have been wronged, AND comes up with a CREATIVE INCENTIVE that helps ALL OF THE CUSTOMERS HE HAS AFFLICTED WITH HIS CHANGING TERMS AND NOT ALLOWING AN OPT OUT OPTION, what good does it really do to accept Chase Bank's DIVIDE AND CONQUER strategy?You are not above your customers, Jamie Dimon. Any success that you derive is because of your customers willingness to follow the rules, and that needs to be a two way street.
Isn't this exactly how economies get into trouble? They do something wrong, then exacerbate the wrongness by rewarding people to keep quiet about the wrongness that has already occurred.
Is that not a part of the frustration YOU FEEL when an occasional internet responder tries to accuse you of being irresponsible because you can't afford an overnight 2% to 5% increase in the monthly minimum payment?
You did nothing wrong. You faithfully paid down your Chase Bank bill, steadfastly followed the rules in place, then had Jamie Dimon approve a monthly minimum payment increased of 150%!
Is the best that Chase Bank can do now is offer a secret phone number that they don't want publicized to the very people who need it the most?
THIS SOLVES NOTHING.
JAMIE DIMON, APOLOGIZE AND REVERSE COURSE.
Monday, July 20, 2009
WAKE UP CALL FOR 2 MILLION CHASE BANK VICTIMS of the 2% to 5% MONTHLY MINIMUM PAYMENT INCREASE, LEARN WHO IS STEALING YOUR THUNDER!
It will take at least 500 to a 1,000 internet protestors to make a dent against the Chase Bank monolith. There may in fact be 10,000, 20,000, even a hundred thousand or more people upset with Chase Bank, but they don't post on the internet nor do they share what they are doing to protest Chase Bank.
I think it is very important for all of you not to just think of this DAILY-PROTEST site and BLOGGERS AGAINST CHASE BANK as simply places to make you feel better as a victim. These two sites are here to inform the uninformed, to motivate those who thought there was nothing they can do, and to DEFEAT CHASE BANK AND MAKE THEM REVERSE COURSE.
What I am saying is, you are very welcome here, but we need MORE people involved. Don't be shy about getting a FREE GOOGLE BLOG, the link is to the right of this column! You don't have to do research. Just tell your Chase Bank horror story on your blog, and just update it once a week.
I am telling you now, if you don't get other people involved, not only will Chase Bank not reverse course, but other banks will follow. STOP BEING FRIENDS with people who won't support you. SPEND NO TIME with them.
I can't tell you the number of people who have always wanted my time, but when it came time to help me, were too busy. I will occasionally talk to them, but I don't spend time with them.
PEOPLE WHO SAY IT CANNOT BE DONE SHOULD NOT GET IN THE WAY OF THOSE WHO ARE ALREADY DOING IT. -George Bernard Shaw
If you have friends who naysay you, that say Chase Bank is too big and powerful, Tell them the saying above by George Bernard Shaw, and ask them to reconsider their negative energy towards your cause. If they won't support you, then DUMP THEM AS YOUR "FRIEND".
If you belong to forums, put links in your signature to this and other protest websites.
Our biggest obstacle is turning out to be the republican party. I say that as someone who first voted for Hillary Clinton in the democratic primary, ad then John McCain last year. The republican party HAS STOLEN the anti Chase Bank energy and converted it into Tea Party Protests.
When people do tea party protests, they are DISRESPECTING YOU. What you are going through as a Chase Bank victim NOW, TAKES PRECEDENCE OVER what MIGHT happen down the road because of higher government spending. Not only that, if Chase Bank wasn't trying to stifle local economies in the three ways I have mentioned several times on this blog, THERE WOULD BE NO NEED FOR STIMULUS PACKAGES AND BAILOUT PROGRAMS!
YOU, as a Chase Bank Victim, are top priority. If you are a republican, CHALLENGE YOUR PARTY TO FOR ONCE, DO SOMETHING FOR THE BLUE COLLAR GUY, JUST ONCE.
Whenever you see a Tea Party Protest, don't be happy, be ANGRY that they are STEALING the publicity that TWO MILLION CHASE BANK CUSTOMERS / VICTIMS SHOULD BE GETTING right now.
TEA PARTY PROTESTS DO NOT SUPPORT YOU, THEY STEAL MEDIA ATTENTION AWAY FROM OUR CAUSE AGAINST CHASE BANK AND ARE NOTHING MORE THAN A VAPID REPUBLICAN TOOL TO MAKE BARACK OBAMA LOOK BAD. I'm saying this as someone who DID NOT vote for Barack Obama last year, either time!
EVEN IF YOU BELIEVE THE TEA PARTY PROTESTS ARE NOT JUST REPUBLICANS TRYING TO GET BACK INTO POWER, THE PROTEST SHOULD WAIT THEIR TURN UNTIL AFTER CHASE BANK IS TURNED BACK!
Be angry at the republicans, be angry at those who carry tea party protest signs but don't give a crap about what Chase Bank is doing to 2 million of their best customers.
Most importantly, would you put up a physical sign with a web address that directs people to your favorite protest blog against Chase Bank? WE HAVE TO REACH PEOPLE who would not think to use the internet to protest against Chase Bank, that can't be done from this website, it has to be done on the streets.
Tuesday, July 14, 2009
WARNING, MINNESOTA ATTORNEY GENERAL SUES NATIONAL ARBITRATION FORUM for FAVORING the CREDIT CARD COMPANIES AGAINST CONSUMERS.
I have been advocating consumers who are being victimized by Chase Bank and their raise in the monthly minimum payment from 2% to 5%, request arbitration. I just want to pass on a heads up that The National Arbitration Forum is being accused of Favoring banking giants such as Chase Bank, Bank of America, Citi Bank, and so on down the line, over the consumer.
I can imagine that if the results are not to the major banks liking, they simply will take their business to another, more "reasonable" arbitrator. It is not that far of a stretch to feel compelled to somewhat manipulate results if your employer will fire you otherwise.
I can imagine that if the results are not to the major banks liking, they simply will take their business to another, more "reasonable" arbitrator. It is not that far of a stretch to feel compelled to somewhat manipulate results if your employer will fire you otherwise.
This is the exact same kind of game playing that allegedly goes on in the food industry business. If a food giant hires a food inspection company to document that they follow safe food handling practices, just how far will the company that has been hired by the food giant go against the very company that is probably paying them for favorable results.
Now we find the same pattern in the finance industry when it comes to arbitration. I still recommend arbitration, just be wary and be tough and mention that you know about THIS LAWSUIT FILED BY THE MINNESOTA ATTORNEY GENERAL AGAINST THE NATIONAL ARBITRATION FORUM and that you expect a fair hearing no matter who is paying their way.
Now we find the same pattern in the finance industry when it comes to arbitration. I still recommend arbitration, just be wary and be tough and mention that you know about THIS LAWSUIT FILED BY THE MINNESOTA ATTORNEY GENERAL AGAINST THE NATIONAL ARBITRATION FORUM and that you expect a fair hearing no matter who is paying their way.
I have read on the internet allegations that some home appraisers may be giving out appraisals that favor the banks agenda on a case by case basis.
The beat goes on.... or should I say, the consumer beating goes on.
HOW YOU CAN HELP! MAKE A DAILY-PROTEST.com sign and put it where others will see it. Daily-Protest.com signs can be placed in a storefront window, a bulletin board at work, or a countertop. Raise curiosity and awareness about how Chase Bank is harming a LOT of of their BEST customers by making a Daily-Protest.com sign.
Monday, July 13, 2009
Is JAMIE DIMON and CHASE BANK about to RETREAT on their 2% to 5% RAISE in the MONTHLY MINIMUM PAYMENT?
There are some hard core Chase Bank haters who are hammering away on the internet, contacting the media, complaining directly to Chase Bank, posting to the Chase Sucks Forum or at Change in Terms dot com, or writing a complaint at Consumer Affairs dot org.
Then there are hundreds of bloggers who are pissed off and will devote entire articles to their hate for Chase Bank. These bloggers don't have a dedicated blog to hating Chase Bank, but they have used their regular blog about coupons, headphones, raising kids, being in love, to suddenly go off topic and complain about Chase bank! I mean, WOW!
Then there are the thousands who are also taking the time to write letters to Consumer Affairs dot org, their congress person, the Office of the Comptroller of the Currency, or the board of directors of Chase Bank, or just complaining to Chase Bank customer service.
Then there are the people who are googling, who have never before googled phrases such as "raise the monthly minimum payment", "OPT OUT", "Change in Terms", or "Chase Bank Protest". I can only imagine the feeling of vindication and rejuvenation they might feel when their google search reveals actual links to blogs and articles where others express similar sentiments such as feeling like they too have been kicked in the stomach, by Chase Bank.
Considering that this is a free google blog, I have still put HUNDREDS OF HOURS into it in front of the key board, plus several dozen more hours actually protesting on locations, even making the protest signs takes time. I can't forget the almost 10 bucks for magic markers to make my protest signs with and free white cardboard stock from Costco.
Therefore seeing the recent spike in readership here is gratifying.
We all are motivating each other. The more hits Daily-Protest dot com and Bloggers Against Chase Bank dot com get, the harder I try. The harder I try, the more people seem to find my blog who then realize they are not alone, nor are they a loan.
On the one hand, I wish my audience was 10 times as large, as then I would know for sure that the messages from this blog are getting out there. On the other hand, my audience could easily be ten times smaller if Chase Bank had taken a different, less violent approach towards their customers.
Don't give up, please show up here every day, say hello. It all helps remind Chase Bank that strangers who don't even know each other or even live by each other, are amassing against them.
Just imagine if each one of you put up a Daily-Protest.com sign where others could see it, ouch!
Fortunately, my own research has led me to the conclusion that Jamie Dimon cannot win. The best chance Mr. Dimon has to save his own job is a very fast retreat from the harsh position Chase Bank has chosen to take against millions of their best, most loyal, never late making a payment credit card customers.
Remember, Mr. Dimon is not even schooled in being a banker, and may I say, it shows.
HOW YOU CAN HELP! MAKE A DAILY-PROTEST.com sign and put it where others will see it. Daily-Protest.com signs can be placed in a storefront window, a bulletin board at work, or a countertop. Raise curiosity and awareness about how Chase Bank is harming a LOT of of their BEST customers by making a Daily-Protest.com sign.
Friday, July 10, 2009
Chase Bank's 2% to 5% Monthly Minimum Payment INCREASE for 2 million customers WILL COST CUSTOMERS BETWEEN 100 MILLION TO 1 BILLION DOLLARS A MONTH!
Jamie Dimon of Chase Bank has mistakenly claimed that Chase Bank is raising the monthly minimum payment from 2% to 5% on 2 million of their most loyal, never make a payment late customers as a way to help them pay down their credit card debt.
Jamie Dimon is misinformed, and it concerns me that some one with so much responsibility and that has so many people counting on him to make intelligent, cognizant, truthful statements, could be so misguided.
How can Jamie Dimon run Chase Bank if he doesn't even understand a principle as simple as the most effective way for consumers to pay down their credit card debts?
To put this as simply as I can, the BEST WAY to get out of credit card debt is to pay off the highest interest rate cards FIRST by making bigger than minimum payments every month. The LOWER INTEREST RATE CARDS are paid the monthly minimum payment every month as the consumer is making larger monthly minimum payments on higher interest rate cards.
When Jamie Dimon raises the Chase Bank monthly minimum payment from 2% to 5% on LOW INTEREST RATE CREDIT CARD LOANS, he is making the most reckless decision he can make to his own customers who have never done him wrong but rather made their payments on time each and every month.
I have made an initial estimation that Chase Bank is COSTING THE AMERICAN CONSUMER BETWEEN 100 MILLION TO 1 BILLION DOLLARS A MONTH because of Chase Bank's "ME FIRST", SCORCHED ECONOMY approach to 2 million of their most reliable, never late paying customers by raising their monthly minimum payment from 2% to 5% on low interest credit card rates.
WILL SOMEBODY, ANYBODY, save us from the theft of our own survival resources by Chase Bank?
HOW YOU CAN HELP! MAKE A DAILY-PROTEST.com sign and put it where others will see it. Daily-Protest.com signs can be placed in a storefront window, a bulletin board at work, or a countertop. Raise curiosity and awareness about how Chase Bank is harming a LOT of of their BEST customers by making a Daily-Protest.com sign.
Saturday, July 4, 2009
REVIEWING WHAT IS EVIL ABOUT CHASE BANK'S 150% INCREASE in the MONTHLY MINIMUM PAYMENT.
What Chase Bank is not saying is that the "one-two percent" that they are blindsiding with a 150% increase in the monthly minimum payment are a million to two million of their most trustworthy, reliable customers who were never late making their payments AND were benefiting from a low interest, life of the loan interest rate!
Chase bank appears to be trying to default their most reliable and trustworthy customers by raising the monthly minimum payment on them by an additional 150% because Chase Bank wins no matter what happens next.What makes the situation completely unacceptable is that Chase Bank is NOT ALLOWING THESE OVER ONE MILLION VICTIMS STRONG to OPT OUT of the change in terms to their pre-existing agreement.
If these one million plus blind sided, previously never late paying Chase Bank customers pay the additional 150% increase in the monthly minimum payment requirement, Chase Bank saves a ton of money by accelerating the pay down on these low interest, life of the loan interest rates, a move that has been aptly labeled bait and switch by an LA Times Headlines.
If these one million Chase Bank customers cannot afford the new 150% higher monthly payment requirement. they will default on the special low interest rate, life of the loan account, the interest rate jumping from 3.99-5.99 percent to as high as 29.99%, and their credit rating will be affected as well.
The other point that NOBODY MAKES is that other credit card companies HAVE NOT raised their monthly minimum payment requirements, and if they do, they will MOST LIKELY OFFER AN OPT OUT OPTION TO THEIR CUSTOMERS, whereas CHASE BANK DID NOT!
If Chase Bank succeeds in raising their monthly minimum payment by 150%, they are basically jumping their payback requirements ahead of all the other banks. This then makes the other banks look bad to their investors and literally forces them to do the same thing. If Chase Bank demands a bigger cut of the monthly minimum payment pie, why shouldn't all the other banking boards do the same thing to customers cannot afford it?
I am actually for higher minimum payments, as long as they are done when someone gets their first credit card, not after they have built up debt under the 2% monthly minimum rule and are using the low interest rate card to pay down that particular bill while paying down higher interest rate cards first, which is EXACTLY how Chase Bank marketed the discount offer to ALL OF THESE CUSTOMERS they are now blind siding.
If Chase Bank succeeds in raising the monthly minimum payment by 150%, consumers will have LESS AVAILABLE MONEY every month to pay other higher interest debts. Chase Bank's demand also suctions much needed money from local economies as people will have absolutely no additional money to spend, even on basic necessisities.
When these consumers credit rating is lowered for defaulting on these Chase bank accounts, they will be paying higher interest rates in the future as well, resulting in less money every month for the local economy.
EVERYBODY is watching to see if Chase Bank succeeds with their "me first, screw everybody else" mind think. Read the consumer affairs dot org link to see how Chase Bank is devastating over a million people come August 2009.http://www.bloggersagainstchasebank.com
Wednesday, July 1, 2009
PLEASE VOTE IN THE LA TIMES IS CHASE BANK EVIL POLL.
Please vote in the LA Times Chase Bank Poll. The article by Dave Lazarus is pretty good, the headline is spectacular, but there are a couple of unfortunate omissions. Mr. Lazarus implies that Chase has defeated the lawsuits against them when they have not by stating that what Chase Bank has done is despicable but possibly legal (the lawsuits are still ongoing).
Mr. Lazarus does not mention opting out. However, the mentioning of bait and switch is very strong and I am very happy that was included in the actual headline of the article, wow!
I find it frustrating that the LA Times IS NOT ALLOWING COMMENTS on this article, a disturbing trend in my opinion. However, to the LA Times and Mr. Lazarus credit, they did put a poll in this article and Chase is just getting pasted! Please join in the fun and vote. It actually does matter.
Although comments are enabled beneath the article, Mr. Lazarius can also be reached by email, which I think is very cool (I always recommend the ultimate in politeness when emailing a writer).
Apparently, internet news etiquette is either comments can be left but the writer may not be contacted, or if comments cannot be left, the writer can be contacted via the internet. That seems to be the case for most articles left on newspaper websites, except for the AP, which appears to not allow either contact with the writers of their articles, nor can comments be left. Yeesh.
Tuesday, June 30, 2009
SOMEBODY BESIDES DAILY-PROTEST ACTUALLY MENTIONS THE ALMOST ONE TRILLION DOLLARS IN CONSUMER CREDIT CARD DEBT.
Well, it had to happen sooner or later. Somebody besides Daily-Protest.com has actually decided to mention the almost one trillion dollars in consumer credit card debt. Yeah the article is offering literature for sale, but at least they are addressing the issue!
I've been mentioning the consumer credit card debt quagmire for the past fews years. My two credit card warning websites Credit-Card-Cap.com and Credit-Protector.com have been up for a few years now.
Finally, Chase Bank is in the news for harming people unnecessarily with their raise in the monthly minimum payment and somebody besides me is actually talking about the consumer credit card debt issue!
The tide is turning!
Monday, June 29, 2009
ANOTHER CHASE BANK RAISES the MONTHLY MINIMUM PAYMENT STORY but the REPORTER MISSES KEY PARTS of the STORY.
I consider this article to be incomplete and seems to give the impression that we the consumer, can do nothing to stop Chase Bank. The article reports the story about Chase Bank raising monthly minimum payments from 2% to 5%, but they leave out critically important information like Chase Bank's refusal to allow the consumer the right to OPT OUT of any change in terms.
The article then quotes Chase Bank and does not even bother to get an opposing viewpoint even though hundreds of blogs are voicing their displeasure with Chase Bank's methods, methods that have yet to be replicated by any other bank.
The article appears to me to try and validate Chase Banks position. You have to reload the story once or twice before you see the comments section appear. The end result is, the article simply reinforces the idea that Chase Bank can do whatever it wants, and we have no say. That of course, is nonsense. Lets fight back, but in a polite way.
Please email the reporter ( KCheatham@wsbt.com ) and politely ask why she missed the issue of OPTING OUT.
HOW YOU CAN HELP! MAKE A DAILY-PROTEST.com sign and put it where others will see it. Daily-Protest.com signs can be placed in a storefront window, a bulletin board at work, or a countertop. Raise curiosity and awareness about how Chase Bank is harming a LOT of of their BEST customers by making a Daily-Protest.com sign.
Friday, June 26, 2009
Another potshot at the Credit Card Reform ACT of 2009.
All the media hoopla over the credit card bill reform act of 2009 passing, yet the right for the consumer to OPT OUT was not included in this bill. The media wrote about the passing of the Credit Card Reform Bill like it was a big deal and we the people should be grateful, bah humbug, we were scrooged.
HOW YOU CAN HELP! MAKE A DAILY-PROTEST.com sign and put it where others will see it. Daily-Protest.com signs can be placed in a storefront window, a bulletin board at work, or a countertop. Raise curiosity and awareness about how Chase Bank is harming a LOT of of their BEST customers by making a Daily-Protest.com sign.
Friday, May 15, 2009
DAY-39, CHASE BANK PROTEST.
Thursday was spent reading and responding to various Chase Bank articles on the net. I have a couple of exciting new things coming up. I will reveal one of them in my next article.
Thursday, May 7, 2009
DAY-32, CHASE BANK PROTEST, RESPONSE to NY DAILY NEWS ARTICLE ABOUT BANK STRESS TESTS.
I tried leaving the following response to a NY Daily News article about bank stress tests. Their software clumped my multi paragraph response together as if it were one long paragraph. My response was also cut off without alerting me where that cut off point would be before I submitted my response. So, this response is for you, NY Daily News.
--------------------------------------------
How come there is no "stress test" for the flow of money back from the consumer to the banks? Why is it only about the banks and the amount of money they actually have in "reserve".
Isn't the biggest cash reserve the american worker and how far their weekly paycheck can be stretched?
Instead of helping to maximize the american worker's weekly paycheck, that paycheck is being contracted by boorish methods such as ridiculously high credit card interest rates and the punishment of anyone who has earned low interest rates because they were never late on a payment.
Labeling a low interest credit rate as a toxic asset, we can do better than that, no?
Stealing frequent flyer miles from the most reliable AMEX customers, then reallocating those same miles from AMEX to Citibank so Citibank can make a sweetheart loan deal with American Airlines, we can do better than that, no?
Chase Bank hitting their own best, most reliable, most trustworthy on time payers with an additional 150% monthly minimum payment on top of the payment they are already making, we can do better than that, no?
Telling people the economy is about to recover even though credit card debt is at ONE TRILLION DOLLARS AND CLIMBING, we can do better than that, no?
Until nationwide credit card debt is lowered from the one TRILLION DOLLARS it currently stands at, the economy WILL NOT turn around.
Credit Card Companies should be using incentive based credit card programs to get more cash flow return from those still working and those who still owe them money, rather than punishment based credit card programs that cause real consumer stress, distress and unrest.
Please join my protest against the Credit Card Industry and Chase Bank, http://Daily-Protest.com
Just bookmark my site and help the sites ranking grow. The other thing you can do is put up a Daily-Protest sign in a storefront window, a bulletin board, or a countertop. -Alessandro Machi
Wednesday, May 6, 2009
DAY-31 CHASE BANK PROTEST and ANOTHER CHASE BANK DOES THE WRONG THING UNTIL A MEDIA CONSUMER ADVOCATE GETS INVOLVED.
 CLICK ON IMAGE TO ENLARGE.
It seems that with each passing day I find another consumer advocate saves a Chase Bank customer from the clutches of Chase Bank indifference and arrogance. It seems as if everyday brings a new story of a media consumer advocate helping a Chase Bank Customer get their money back from some type of Chase Bank shenanigans.
Chase does the right thing only when a consumer advocate with newspaper ties gets involved.
Help Daily-Protest.com grow.CHASE BANK PROTEST-DAY 9. HOW YOU CAN HELP THE DAILY-PROTEST.com CREDIT CARD PROTEST GROW WITHOUT EVEN PROTESTING YOURSELF, AND IT IS FREE.
Tuesday, May 5, 2009
DAY-30, Chase Bank Protest, Chase President owes an apology to elementary students he misled, and he owes them a 10% interest savings account as well.
 Keith Schuck, President of Chase Bank, misleads elementary school students by telling them they can save their money at a 10% interest rate in a bank! This deception is spun even as Chase Bank continues to do massive harm to some of their most loyal credit card customers. Chase bank did not allow hundreds of thousands of pay on time customers with low interest rate offers an "opt out" option after Chase Bank changed pre-existing agreements with people like this childs parents. Harm the parents, deceive the child, has kind of an anti-heroes ring to it.

Keith Schuck, president of Chase Bank, recently spoke to elementary school about the importance of savings accounts. Mr. Schuck chose to use 10% for the interest rate when he taught these young minds how to calculate how their savings can grow if they put their money into a savings account.
I consider what Mr. Schuck did a form of child abuse. Chase bank has no problem firing a customer service employee who took off a couple hundred dollars worth of overdraft penalty fees for a customer who somehow racked up well over a thousand dollars worth of these penalities even though the fired Chase bank employee did it so the person could pay their rent!
I consider what Mr. Schuck did a form of child abuse. Chase bank has no problem firing a customer service employee who took off a couple hundred dollars worth of overdraft penalty fees for a customer who somehow racked up well over a thousand dollars worth of these penalities even though the fired Chase bank employee did it so the person could pay their rent!
Keith Schuck, to make things right, should offer each of these children that he misled into thinking they could get 10% interest on a savings account, a 10% interest bearing college savings account. Unfortunately that would require Mr. Schuck honor his own words, spoken to young, trusting minds.
Chase bank has no problem changing terms on their NEVER LATE paying customers without offering them a respite known as an "opt out" option. Chase bank offers the parents of these school children approximately 0.01 percent interest on their savings accounts, approximately 1000 times LESS than what he told these elementary school kids they could get if they opened a savings account in his branch.
Isn't it just a bit outrageous for Keith Schuck to condescend to children who look up to his distinguished position as president of a huge bank by suggesting to these kids they could save money at 10% interest? Is it acceptable for the president of Chase Bank, a Bank that probably has put many many people closer to bankruptcy or eviction because of insufferable addiction to money collected via penalities, to misrepresent interest savings rates to the sons and daughters of the very people Chase offers .01% interest to?
If Keith Schuck wants to make it right concerning his recent visit to an elementary school in which he used 10% interest savings rate as an example, he will offer each child that heard his words a savings account with a 10 percent interest rate attached to it. If Mr. Schuck can't or won't do this, it just becomes additional proof that he is a monster of deception and doesn't even care who knows it.
Help Daily-Protest.com grow.CHASE BANK PROTEST-DAY 9. HOW YOU CAN HELP THE DAILY-PROTEST.com CREDIT CARD PROTEST GROW WITHOUT EVEN PROTESTING YOURSELF, AND IT IS FREE.
Saturday, May 2, 2009
DAY-27, CHASE BANK PROTEST - name one CELEBRITY that has publicly chastized Chase Bank or the Credit Card Industry.
Have you heard or seen any celebrity, any famous person, anybody person of note, say anything about what the credit card companies are currently doing to the american people? Has anybody of prominence questioned the logic of reducing the spending capacity of millions of americans while also raising interest rates on their credit cards, when they should at the very least be lowering the interest rate?
It's so simple. Cut people's credit lines if you must, but accompany that cut with LOWER INTEREST RATES, NOT HIGHER.
If you have heard of any famous person railing against the credit card industry, PLEASE respond to this topic and provide a link. If you have not heard a celebrity railing against the credit card industry, then maybe any "change" that is going to happen, is going to have start with people like you and me.
I know congress is making "changes" and passing legislation, but they have given the credit card companies a YEAR to wreak havoc on middle america, and the credit card companies have already done their damage.
-------------------------
Today my mother made an interesting comment. "I didn't realize how much your father did in the yard outside". Indeed.
Today my mother made an interesting comment. "I didn't realize how much your father did in the yard outside". Indeed.
I am working on the other side of my supersized protest sign, adding in "Daily-Protest.com". I am planning a protest for tomorrow (Sunday, May 03, 2009). I don't know which Chase Bank I will show up at, I'll probably decide at the last minute.
Corporate sponsored credit card abuse against the american people is a bigger issue than whether you are a democrat or republican.
Take Care.
Help Daily-Protest.com grow. CHASE BANK PROTEST-DAY 9. HOW YOU CAN HELP THE DAILY-PROTEST.com CREDIT CARD PROTEST GROW WITHOUT EVEN PROTESTING YOURSELF, AND IT IS FREE.
Thursday, April 30, 2009
DAY-25 CHASE BANK PROTEST. I COULD NOT PROTEST TODAY. HAD TO GIVE OUR DOG A REALLY LONG BATH, HOWEVER...
 CHASE OR MY CUTE FACE, CLICK HERE TO SEE ME EVEN LARGER.
I spent from 2:30am to 7:00am resizing my Daily-Protest.com Blog. I first spent a couple of hours meticulously strategizing the proper width of each column and the middle column as well. I then had to resize every photo in the main column and in the far left column as well.
Should I really say I did not protest today when I spent five hours making this blog more presentable for those who check it out?
I also spent the afternoon caretaking our 13 year old shitszu. My time was spent cleaning her eyes, trimming back the hair from in front of her eyes, then a really long bath. I don't do the pour water over the dog routine. I actually keep our dog in a metal tub with lukewarm water so she is immersed completely except for her back and head.
She actually looks pretty good right now. However, within a day or two the itching will start again, followed by the bleeding. I hope she isn't suffering.
Doesn't she look good right now for 13 x 7 years, which equals 91 in human years. Kind of odd how I am leading a credit card revolution but I have to take time out for our dog. I also reinforced my Chase, Keep Your Word sign. It is really large and has developed some creases that make the sign bend in two whenever the wind blows.
So today was a reload day, hopefully tomorrow will be an on the street Chase Bank protest day.
Subscribe to:
Posts (Atom)